

The COVID-19 pandemic drove a sharp growth in digital payment in Cambodia. (AKP)
As digital payments scale across Southeast Asia, they are transforming from a consumer convenience into economic infrastructure — powering financial inclusion, productivity and regional trade.
From cash-heavy to digital-first
Digital payments are no longer emerging in Southeast Asia — they are becoming dominant. By 2028, 94% of e-commerce payments will be digital, with non-digital methods shrinking to just 6%, down from 13% in 2023.
A US$325B engine by 2028
SEA’s e-commerce payment value is expected to grow from US$138 billion (2023) to US$325 billion (2028) — driven almost entirely by:
- real-time domestic payments;
- mobile wallets;
- “Buy Now Pay Later” payment (BNPL).
Traditional cards alone are no longer the growth driver — local rails and wallets are.
Designing around low card ownership
With credit card penetration as low as 6 to 30% in major SEA markets:
- QR payments, wallets and BNPL have become the default on-ramp
- millions of consumers and SMEs can transact without formal banking
For businesses, especially SMEs, digital payments deliver:
- lower fees via domestic real-time rails;
- faster settlement and improved cash flow;
- no need for costly POS infrastructure (QR-based payments).
As a result, small-ticket transactions become viable, boosting retail, tourism and local supply chains.
Payments are quietly fixing fragmentation
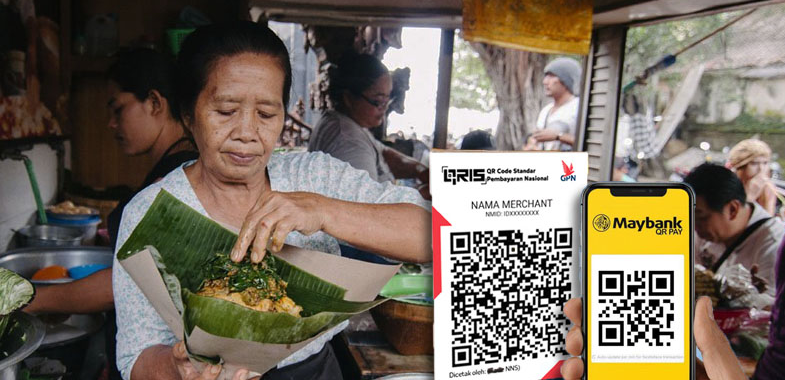
Interoperable domestic systems (QRIS, PromptPay, DuitNow, FAST, etc.) are:
- reducing friction in cross-border payments;
- enabling local merchants to accept foreign wallets;
- supporting tourism and intra-ASEAN trade.
Payments are becoming a practical layer of ASEAN economic integration.
From payment rails to economic infrastructure
Digital payments now sit at the centre of SEA’s digital economy by powering e-commerce and super-apps, generating data for credit scoring and financial services, accelerating formalisation and inclusive growth.
If interoperability, trust, and security scale alongside adoption, digital payments could double the impact of SEA’s digital economy.
About The Author
One thought on “Beyond Convenience: Powering SEA’s Economic Infrastructure with Digital Payments”