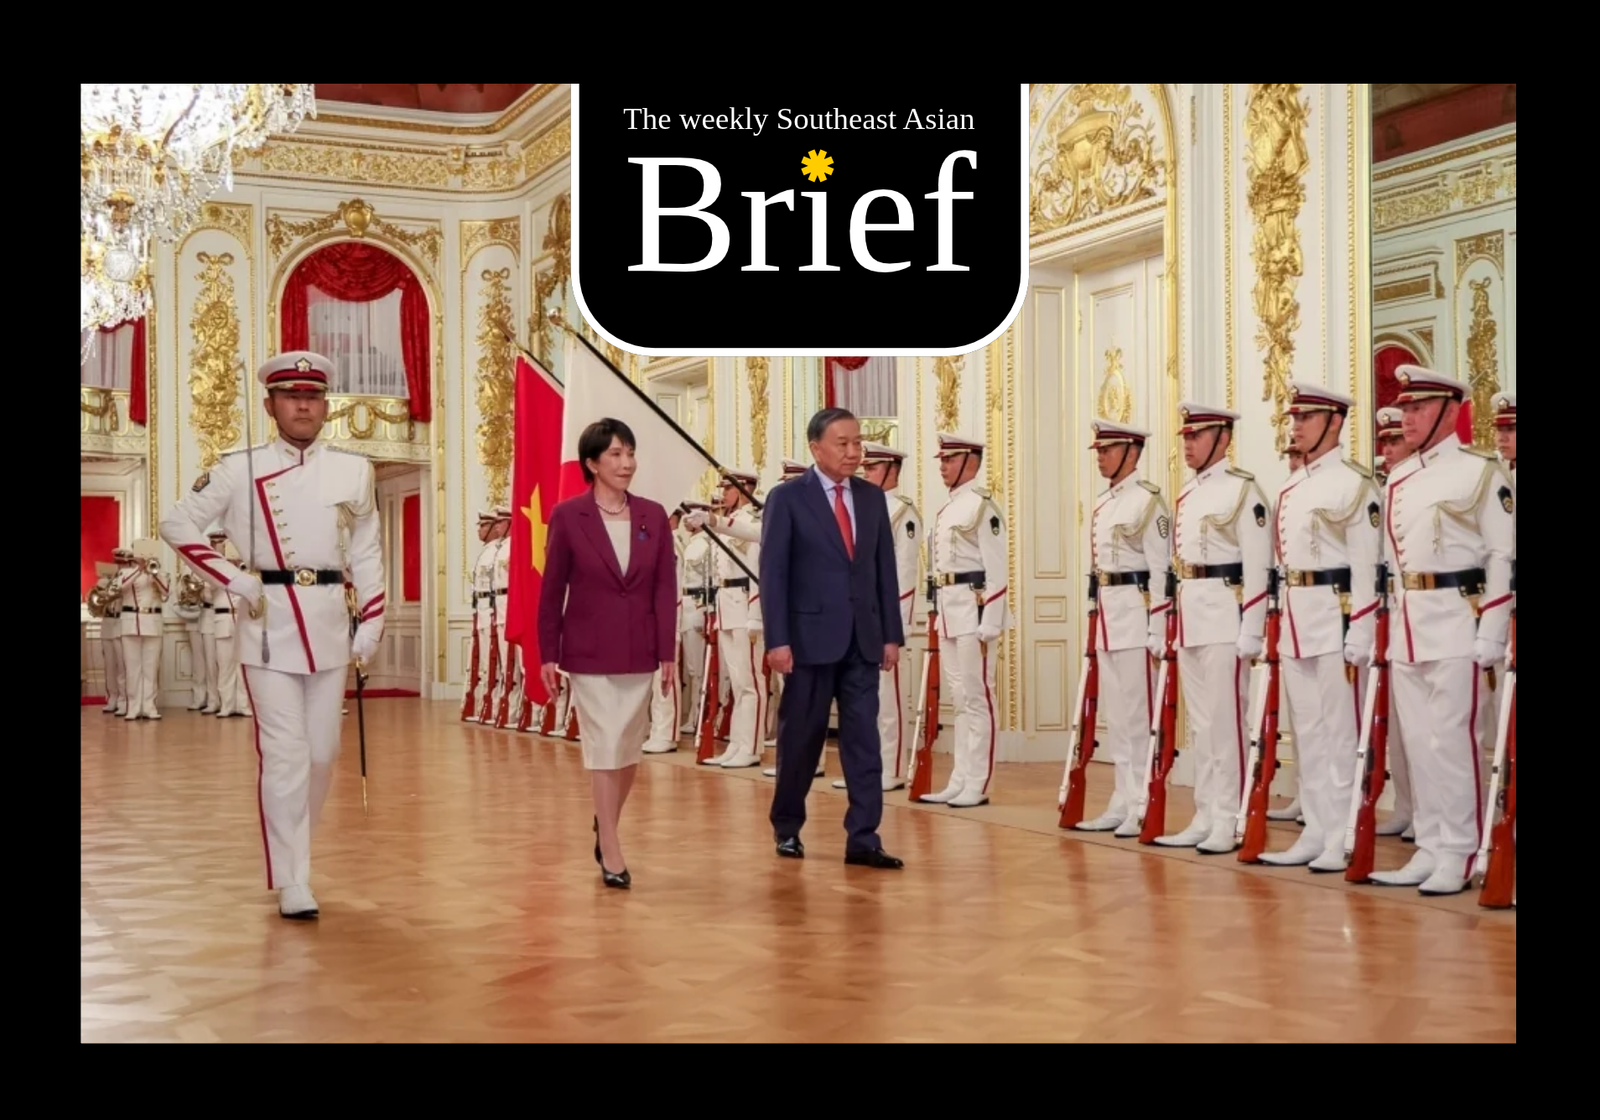
President Tô Lâm and Prime Minister Sanae Takaichi at the State Guest House in Tokyo, 9 November 2026 (Japan’s Cabinet Public Affairs Office)
On 9 November, during an Official Visit to Japan, General Secretary of the Communist Party of Vietnam (CPV) and State President Tô Lâm and Japanese Prime Minister Sanae Takaichi adopted a Joint Vision Statement and agreed to “look into the possibility of identifying and implementing cooperation projects in critical minerals”. The same day, Japanese trading house Sojitz signed a Memorandum of Understanding (MoU) to acquire a 5% stake in Masan High-Tech Materials (MSR), Vietnam’s leading tungsten producer.
The visit came as Beijing squeezed Japan’s access to critical minerals. In January, China’s Ministry of Commerce banned dual-use exports to Japanese military end users, explicitly tying the move to Tokyo’s stance on Taiwan, and has since cut supplies of several rare earths and gallium to Japan to near zero. This has made Tokyo’s search for alternative suppliers more urgent, raising the question of whether Vietnam’s deposits can help.
The gap between Vietnam’s potential and its output remains wide. The US Geological Survey cut its estimate of Vietnam’s rare earth reserves from 22 million to 3.5 million tonnes, and the country produced only 150 tonnes in 2025, against 270,000 tonnes in China. Japan, which imported around 90% of its rare earths from China in 2010, had only reduced that share to about 60% by 2020. Ties are nonetheless close: trade reached 51.4 billion US dollar in 2025, and Japan is Vietnam’s largest development aid provider and third-largest investor.
Read closely, the summit reveals a negotiation over where value will be added, and is not meant to be a supply deal. In May, the two leaders explicitly referred to rare earth supply chains in Vietnam. Six months later, the Joint Vision Statement does not mention rare earths, frames cooperation “according to the conditions and needs of each side” and even puts “strategic autonomy” in its title, while none of the 11 official documents signed in Tokyo concerns minerals. Hanoi intends to keep control of its resources. It bans ore exports and restricts refined exports, and a draft rule would keep domestically mined rare earth products off the export list for now. In return, it wants energy and finance from Japan, and secured a Japan International Cooperation Agency loan for the O Mon 3 power plant and an MoU on nuclear power during the Summit.
If Vietnam can ease any part of Japan’s squeeze in the short term, it is on tungsten rather than rare earths. Vietnam is the world’s second-largest tungsten producer, Japan is one of China’s largest tungsten importers, and MSR’s Nui Phao is, according to the company, the largest operating tungsten mine outside China by reserves. Hanoi is spreading this asset across buyers. In September, the US-based Elmet Group agreed to buy a 4.99% stake in MSR. Rare earths, by contrast, remain at the testing stage, with an 18-month pilot to process 100 tonnes of Dong Pao ore, and South Korea is ahead of Japan, having signed a joint research agreement with Vietnam in April. Money also lags behind rhetoric: new Japanese investment in Vietnam fell 75% year-on-year in the first quarter of 2026.
A competing reading sees Tokyo enlisting Vietnam as an alternative to Chinese supply, something Japan has tried before. After China halted rare earth exports to Japan in 2010, the Dong Pao mine was expected to cover about 10% of Japan’s demand. Still, Japanese investors, including Sojitz, abandoned it when Chinese oversupply crashed prices. Today, Tokyo’s main hedges lie elsewhere, notably a deal to buy at least 5,000 tonnes a year of neodymium-praseodymium oxide from Australia’s Lynas until 2038, backed by a price floor. Vietnam, meanwhile, keeps its options open, having also committed to explore critical minerals cooperation with China in April.
The stakes are also regional. In 2024, more than half of China’s rare earth imports were supplied by Malaysia, Laos and Myanmar, the latter remaining volatile since the Kachin Independence Army captured sites producing roughly half of the world’s heavy rare earths. Malaysia, host of the world’s largest single rare earth processing plant, is both a model and a rival for Vietnam. Competition among outside powers, from the European Union to the United States, strengthens Hanoi’s hand, but the sector carries environmental costs, as illegal mining has polluted Mekong tributaries in neighbouring countries.
The Tokyo summit will likely strengthen the partnership, but Vietnam is unlikely to ease Japan’s rare earth squeeze in the near term. Over the next 12 to 18 months, cooperation will most likely deepen in tungsten, energy and finance, while rare earths stay at the pilot stage. The real test is whether Tokyo backs a processing project in Vietnam with state funding, long-term purchase contracts and a price floor, as it did with Lynas. Hanoi will set the pace, as it will only reconsider rare earth exports once its processing chain matures.
The second Vietnam-Japan vice-ministerial “2+2” foreign and defence consultation, due in December, will be the first marker showing the direction of this cooperation, and test whether economic security gets concrete follow-up. The expiry on 10 January 2027 of China’s pause on its October 2025 rare earth controls will matter to all of Vietnam’s buyers. Finally, the closing of the Sojitz deal and the Dong Pao pilot results will show whether Japanese capital moves from tungsten to rare earths.
Vietnam’s model of keeping ores at home to attract processing capacity may spread across Southeast Asia. However, as long as China dominates separation and magnet-making, a Vietnamese plant relying on Chinese inputs would diversify geography, but would not really diversify supply. The regional contest is over who offers a credible path from resource supplier to higher-value producer, and Japan’s strongest cards in this game are technology and finance.
About The Author