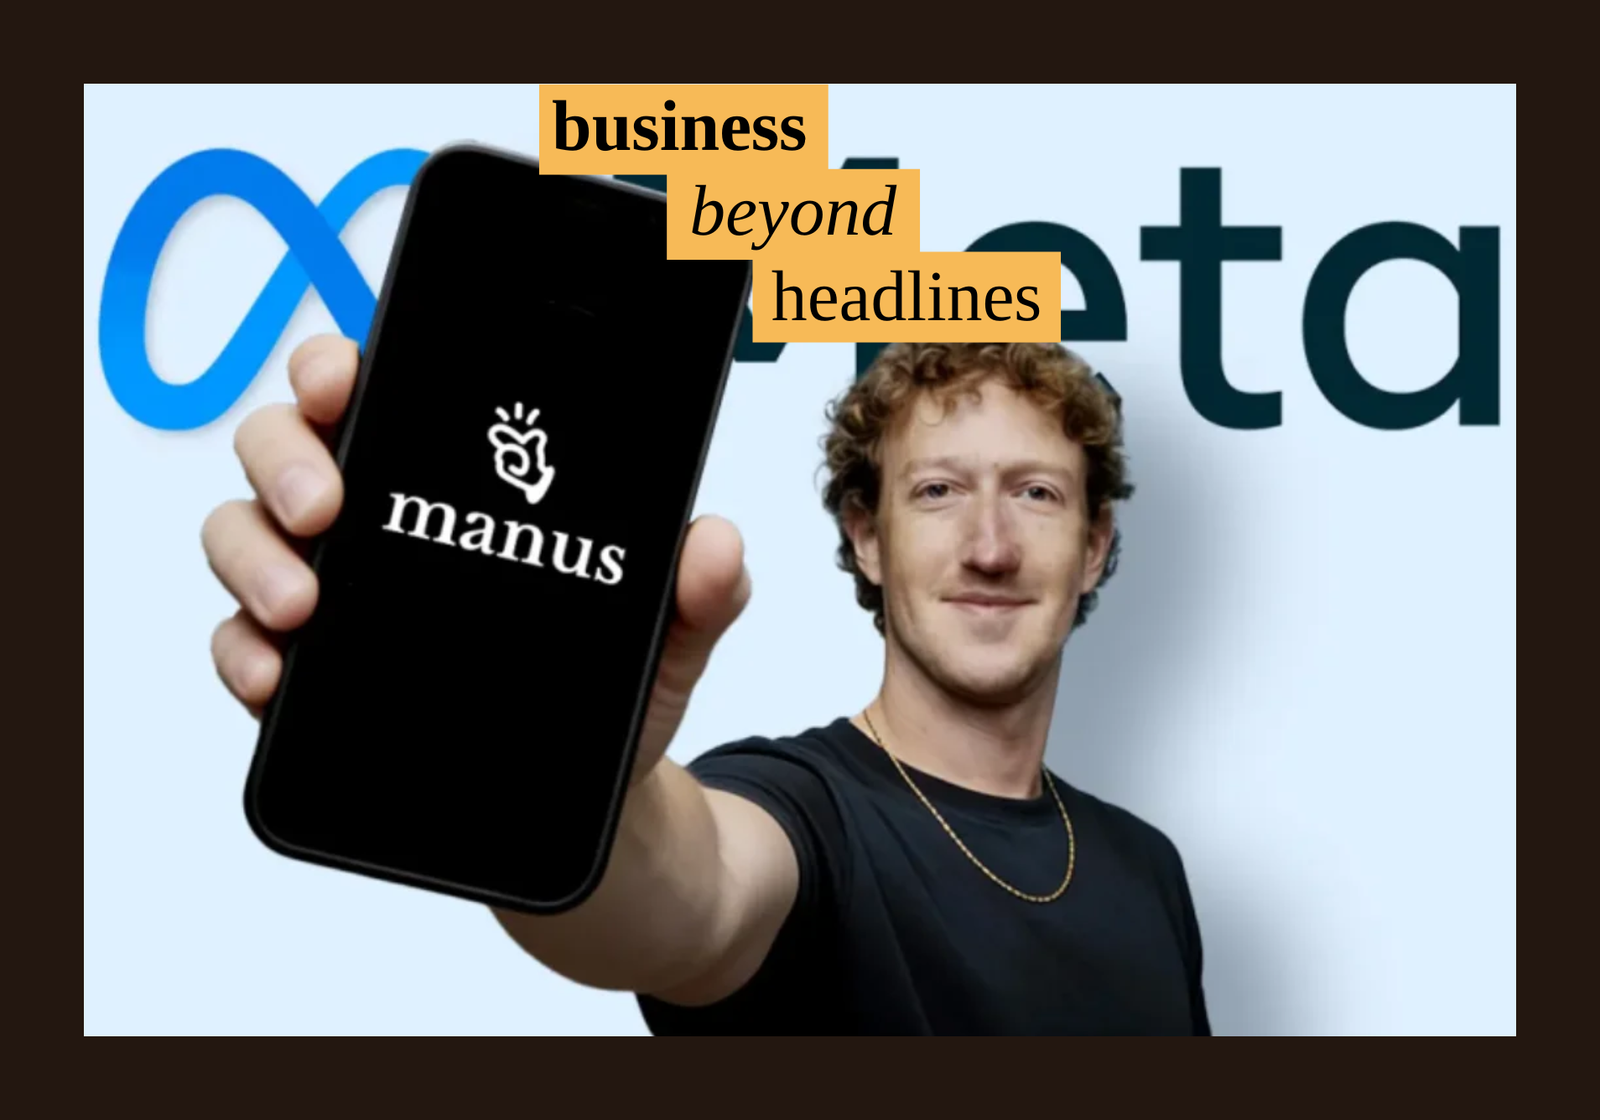
llustration of the acquisition of Manus by Meta. (Mobile App Daily)
From Rising Star to Shooting Star
In mid-June 2026, Meta Platforms began dismantling its 2 billion US dollar acquisition of the Manus platform following a new regulation on Chinese companies investing overseas issued by the China State Council (which refers to China’s government cabinet), which effectively banned the acquisition of Manus by Meta.
Manus is originally an AI company founded in China. In March 2025, Manus provided ‘the world’s first Agentic Generative AI’. The agents it has developed can autonomously browse websites via cloud-based virtual machines and carry out complex tasks. In July 2025, Manus announced its relocation in Singapore and its acquisition by Meta in November. Manus is not the only Chinese company that tried to adopt a more flexible posture in the growing geopolitical conflicts with the small Southeast Asian city-state. Chinese companies invested more than the US in Singapore in 2025 in all indexes, whereas the percentage of Chinese foreign direct investment (FDI) in Singapore also soared, a phenomenon known as the “Singapore washing”.
However, Manus’ attempt of copying this experience ended up in a quiet financial and administrative purge from Chinese regulators and new rules in curbing overseas investment by Chinese investors.
In retrospect, why did China impose the ban? Does that mean the ending of the flux of talents and capital between China and the US? What does the new regulation mean?
Deliberation behind the Regulation

Information declaration page of the NDRC titled as the following: “the Office of the Operational Mechanism for Security Review of Foreign Investments made a security review decision over the acquisition of Manus project by foreign capital”. (NDRC)
To understand the rationale behind the regulatory decision, it is necessary to examine why China chose this particular agency among its many regulatory bodies to intervene in the Manus transaction.
The first public indication of official concern emerged during a Chinese Ministry of Commerce press conference on January 8, when the spokesperson specifically referenced compliance issues involving “export controls, the import and export of technology, and foreign investment.” This statement signaled that the authorities viewed the transaction through the lens of both technology governance and national security.
The final decision regarding the Manus deal was ultimately made by the Office of the Operational Mechanism for Security Review of Foreign Investments (OOMSRF), which operates under the National Development and Reform Commission (NDRC). The OOMSRF was established pursuant to the Foreign Investment Law (FIL) and the subsequent Measures for the Security Review of Foreign Investment issued by the State Council. In many respects, the OOMSRF resembles the Committee on Foreign Investment in the US (CFIUS), serving as China’s principal mechanism for reviewing foreign investments that may affect national security.
Among Beijing’s major regulatory instruments, only technology export controls and foreign investment security reviews can have ex post (meaning regulatory intervention occurs after a transaction or activity has already taken place) effects. By contrast, regulations governing cross-border data transfers and antitrust reviews are generally ex ante (meaning approval or review is required before a transaction or activity can proceed), requiring approval before transactions or activities proceed. The choice of the OOMSRF therefore provides important insight into how Chinese authorities interpreted the Manus transaction, suggesting that the authorities viewed the Manus deal as a deliberate attempt to bypass Chinese regulatory oversight while simultaneously complying with requirements imposed by the US Treasury during the same period. This interpretation may explain why official documents referred to the matter as the “Manus Project” (Manus 项目) rather than focusing on any specific corporate entity, as Manus is theoretically a Singaporean entity. The wording thus avoided the legal status of the entities but focused on the staff members and actual programming which was transferred to Singapore in this case.
The use of the foreign investment security review mechanism also reflects the cautious and somewhat conflicted policy approach adopted by Chinese authorities. On one hand, regulators were clearly dissatisfied with Manus’ decision to operate outside the established legal framework in a highly sensitive technological sector, as it sets a worrying precedent, leading more Chinese AI companies to move their operations abroad.
On the other hand, Manus’ AI activities were not considered significant enough to justify the most severe enforcement options, such as criminal investigations. Given the considerable public attention the company had already received in Chinese media, such a criminal investigation would raise serious concerns for private sectors and may damage the confidence in decision making predictability.
Ultimately, the authorities appear to have opted for a compromise. By employing the foreign investment security review mechanism and framing the matter as the “Manus Project,” they left open the possibility that some form of the acquisition could proceed, provided that data, operations and other sensitive assets related to mainland China remained within China and were not transferred abroad.
The new regulation on the investment added another layer of failsafe for Chinese regulators to stop or pause such projects and investments. The new regulation defines overseas Chinese investment as “activities in which investors within China directly or indirectly acquire ownership, control, operational management rights and other related interests in overseas enterprises or assets”, which again adopted a penetrating consideration that focuses on the real control of companies rather than paperwork.
The regulation also clarified that if any state imposes discriminatory measures against China in the areas of investment and business operations, upon requests of Chinese investors, the Chinese regulators may take countermeasures that may apply to foreign organisations or individuals participating in such measures. This means that if a multinational corporation terminates investment-related transactions with Chinese companies in order to comply with its home country’s export controls or sanctions requirement, Chinese regulators may punish the action accordingly.
The Necessity for Dual Compliance
Illustration of different AI LLM platforms. (Unsplash/Saradasish Pradhan)
After the acquisition took place, China Central Television’s Wechat Account specifically interpreted the decision as a ban on “illegal overseas washing” and a national security issue. However, this is not in contradiction with the continuous encouragement of foreign investment in China, with most state-led media keeping their news reports last year praising Manus and the acquisition.
Another famous Chinese AI company Miromind reportedly to have been warned by Chinese regulators in March and thus created a strict firewall between Chinese and overseas operations, which is likely to be the new model for future Chinese AI start-ups to operate in Singapore and beyond. Meanwhile, major Chinese IT companies like Alibaba or Tencent, or other AI companies like Zhipu AI or Miromind showed no sign of cutting their existing offices in Singapore or Indonesia, nor slow their pace in business expansion overseas.
As such, the regulatory measures of Manus reflect not a complete decoupling, but rather a massive reorganisation with the border of commercial creativity and national security of China.
For now, the State Council has not yet published a detailed catalogue in overseas investment, the catalogue is expected to be released before the validation of the regulation on July 1st. It is therefore necessary to remain vigilant to the detailed catalogue likely to be released before the validation of the new regulations, apart from the predictable limits on AI, semiconductor and quantum computing.
Against that backdrop, three operational recommendations are to be considered by businesses and investors with exposure to Chinese technology firms.
Treat dual compliance as a permanent business requirement
The Manus case demonstrates that compliance with one jurisdiction no longer guarantees compliance with another. Companies operating between the Chinese market and its non-Chinese counterparts should assume that investment, technology transfer and acquisition decisions will increasingly be scrutinised by multiple regulators with potentially conflicting requirements
Abandon the assumption that overseas incorporation provides regulatory insulation
China’s new outbound investment rules focus on actual ownership, control and operational management rather than formal registration. Investors should therefore assess exposure based on where talent, technology and decision-making authority reside, not simply where a company is incorporated.
Prioritise partnerships over acquisitions in sensitive sectors
As Beijing increases scrutiny of overseas technology transfers, licensing agreements, joint ventures and research partnerships may prove more viable than outright acquisitions, particularly in AI, semiconductors and other strategically sensitive industries.
This kind of analysis is the work Kala Advisory does for businesses operating in Southeast Asia. We help companies identify the regulatory and geopolitical risks that standard due diligence often misses, from shifting investment controls to the growing overlap between national security and commercial policy. For tailored intelligence on the risks covered here, visit kala-advisory.com.
About The Author